
Open this photo in gallery:
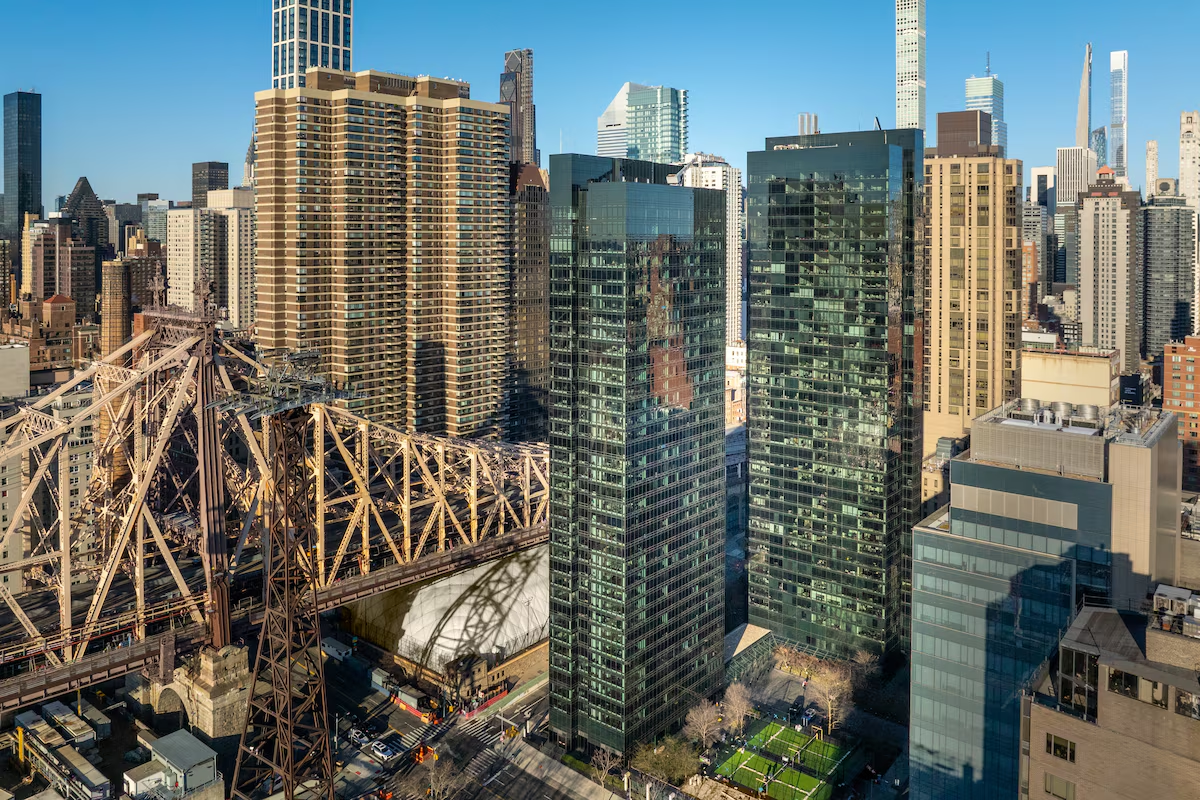
GO Residential REIT’s One Sutton Place North and Two Sutton Place North in Manhattan, New York.Evan Joseph/Supplied
H&R Real Estate Investment Trust unitholders voted down a proposed $3.4-billion takeover by a consortium led by GO Residential Real Estate Investment Trust, a rare investor revolt against a friendly offer backed by management and the REIT’s board.
The failed vote turned what had been a friendly deal into a hostile transaction, with GO going to court to collect a $102-million termination fee from H&R. In a filing late Friday with the Ontario Superior Court of Justice, GO claims H&R founder and chief executive officer Tom Hofstedter and the REIT’s board breached their obligation to support the takeover.
H&R and GO announced the deal in August. Since October, GO alleges Mr. Hofstedter and the H&R board have turned their focus to “appeasing certain unitholders in an attempt to save themselves” at the expense of the proposed acquisition.
H&R declined to comment on GO’s lawsuit. When the transaction was announced in August, it contained termination or break-fee agreements typical in takeovers. Early Friday, H&R said that that none of these payments are triggered by the unitholder vote. Later in the day, GO announced it would go to court in an attempt to force payment of the break fee.
Opinion: H&R REIT takeover deal: A vote of no confidence
On Friday, H&R independent lead trustee Stephen Gross said in a press release that the board will respect the vote against the transaction and launch a plan that includes “a board refreshment process that will include CEO succession planning.”
H&R will roll out an investor-friendly property sale strategy, selling individual properties or entire portfolios to create what Mr. Gross called “a simplified value-driven REIT.”
H&R highlighted the possibility of selling all of the REIT’s industrial real estate, which makes up 20 per cent of its assets and were valued a $1.4-billion in the takeover.
H&R will retroactively pay monthly dividends and intends to declare a special cash distribution of approximately $2.30 per unit before the end of the year. In recent months, the REIT has sold a number of properties.
“In terms of where we go from here, potential changes with management and board will be topical,” said Bank of Nova Scotia analyst Mario Saric in a report on Friday. He said H&R’s short-term plan to sell properties and return cash to unitholders is a “positive” for the REIT’s owners.
The failed takeover was over a year in the making.
In February 2025, after several years during which the REIT underperformed peers, H&R’s board launched a strategic review of its 107-property portfolio of residential, industrial and office real estate. In August, the REIT announced a stock-and-cash deal with GO that included a significant investment by Mr. Hofstedter’s family.
Multiple institutional investors and two proxy advisory services criticized the offer, in part because of the terms offered to Mr. Hofstedter. The deal would have seen the CEO’s family company pay $1.56-billion to acquire properties that H&R held at a book value of $1.19-billion, according to regulatory filings. Mr. Hofstedter founded H&R in 1996 and owns 44 million units in the REIT.
In a report last month, proxy adviser Institutional Shareholders Services Inc. said H&R’s owners should vote against the offer because of “concerns over the sale process, conflicts, deal logic and whether disinterested unitholders are capturing fair value relative to insiders.”
Under the terms of the failed transaction, GO planned to buy H&R residential properties in New York and across the U.S. Sunbelt, which combined make up 66 per cent of H&R’s portfolio.
GO executives said they plan to continue expanding the REIT’s portfolio of luxury high-rise properties in New York and other major U.S. cities.
“We are disappointed by this outcome,” said GO CEO Joshua Gotlib in a press release. “Our focus remains on protecting the interests of our unitholders and the long-term success of our business.”
The industrial properties were to be sold to three institutional investors, U.S. private equity giant Blackstone Inc., Toronto-based Crestpoint Real Estate Investments Ltd. and the Montreal-based Public Sector Pension Investment Board.
On Friday, the price of units closed up by 4 per cent at $9.75 on the Toronto Stock Exchange. The price of GO units also rose 4 per cent to close at US$7.83 on the TSX.
In recent weeks, a number of H&R’s institutional investors publicly stated they would vote against the takeover, over concerns with the deal’s value and Mr. Hofstedter’s role. The asset managers that have come out against the deal include Mill Pond Capital LLC, Smead Capital Management Inc., RBC Global Asset Management, Sandpiper Group and Scheer Rowlett & Associates Investment Management Ltd.
Editor’s note: An earlier version of this article incorrectly reported the book value of certain properties held by H&R as $11.98-billion. The correct figure is $1.19-billion. This version has been corrected.