
Open this photo in gallery:
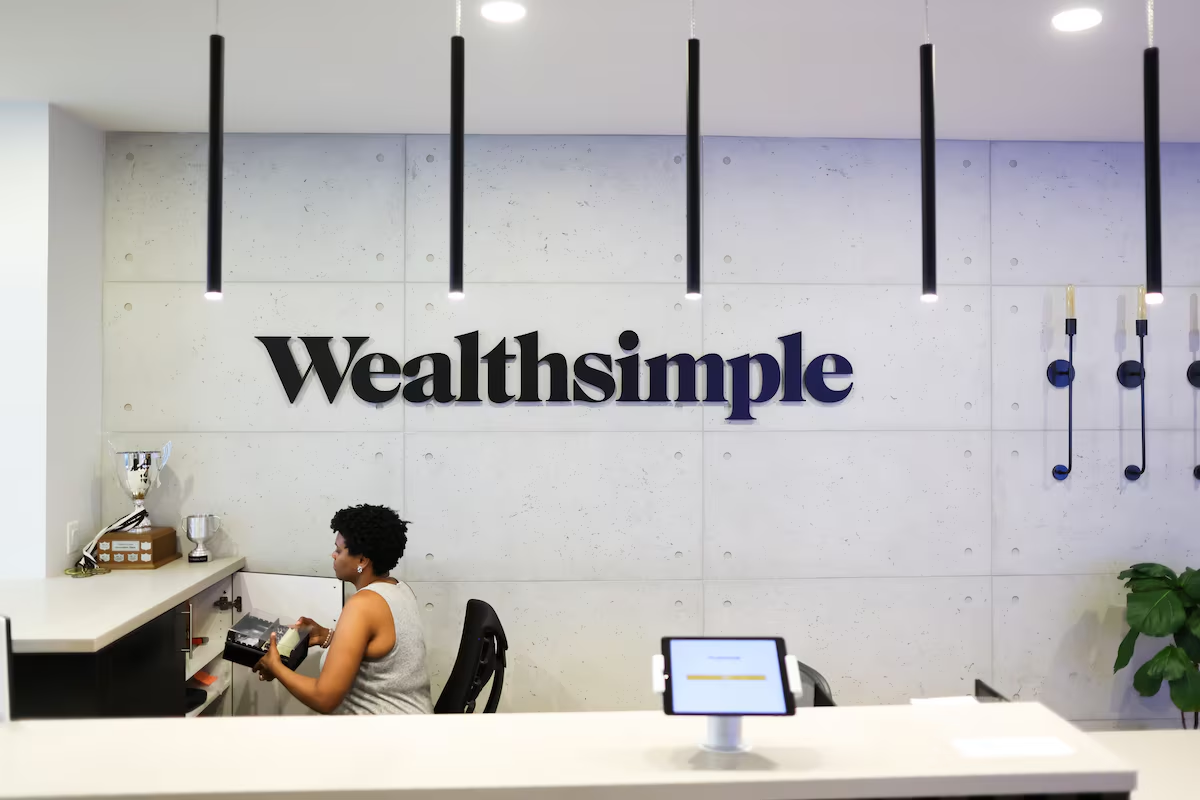
Employees work at Wealthsimple’s Toronto office. The Canada Post partnership is raising hopes that Wealthsimple will help fill some of the service gaps left after conventional banks pared back their physical branches over the past decade.Cole Burston/The Canadian Press
Wealthsimple Technologies Inc. says its cash deposits have nearly quadrupled since it launched its Canada Post partnership earlier this year as part of a broader push to reach customers underserved by the big banks.
In January, the financial services company and the Crown corporation announced a new service that allows customers to make cash deposits through their local post office. Danish Ajmeri, senior director of banking product at Wealthsimple, told The Globe and Mail that cash deposits nearly quadrupled between March and October, when they reached $26-million in one month. Total transactions amounted to more than $130 million.
The collaboration is raising hopes that Wealthsimple will help fill some of the service gaps left after conventional banks pared back their physical branches over the past decade as more consumers and retailers shifted to digital banking platforms. That’s often left rural and remote communities with poorer access to banking services.
But skeptics question whether Canada Post, which has seen declining mail delivery and had a record loss of $1.57-billion last year, can keep the initiative going as a long-term solution to the retreat by traditional banks.
Wealthsimple said one in five deposits were placed by customers outside of cities with a population of at least 100,000, with 18,000 deposits in communities of fewer than 30,000 people, and more than 5,000 deposits in even smaller communities, including in the Yukon and Nunavut.
Wealthsimple launches AI assistant for clients, plans to allow third-party AI tools in 2027
Postal banking is hardly a new concept in Canada, but expanding financial services offered through Canada Post is an idea that has gained new momentum as the postal service and its union look for new sources of revenue.
Facing annual losses of more than $1-billion, the Crown corporation has been trying to tap into the gaps left by departing banks. Canada Post is “uniquely positioned to fill some of these demands” with its network and reach, spokesperson Lisa Liu said in an e-mail.
Anthony Quinn, President of the Canadian Association of Retired Persons, or CARP, called the partnership with Wealthsimple good news for seniors and a “sensible match.”
The number of physical bank branches per 100,000 adults fell by 15 per cent between 2012 and 2021, according to data from the Canadian Bankers Association, a trade association representing 60 domestic and foreign banks in the country. The average travel distance to a physical bank nearly doubled for rural residents who lost their last local branch.
For seniors, greater distances to get to the bank bring difficulties in arranging transportation or the need to rely on someone else entirely to help manage their money, Mr. Quinn said.
The ability to deposit cash at a post office is a good start, Mr. Quinn said. But Wealthsimple’s and other partnerships between Canada Post and the financial sector haven’t gone far enough in addressing the needs of communities left behind by departing banks, he added.
Seniors often need in-person support from bank tellers. Even Wealthsimple requires setting up an account and a smartphone app, “which can still present a barrier for some of the people who most need accessible local service,” Mr. Quinn said.
Jerry Buckland, an economics and international development studies professor at the Canadian Mennonite University in Winnipeg, said small rural businesses also need more services beyond basic transactions. They need access to credit, investment advice, payroll and payment services from someone who understands their business.
Wealthsimple raises funds at $13.8-billion valuation as it seeks to rival banks
The jury is still out on whether the Wealthsimple partnership will succeed in the long run, Mr. Buckland said, pointing to Canada Post’s short-lived deal with Toronto Dominion Bank in 2022.
That partnership promised to provide short-term loans to residents of rural, remote and Indigenous communities. But the program ended just weeks after inception, with TD citing unspecified processing issues.
In 2025, Canada Post announced a new partnership with fintech startup Koho Financial Inc., which provides a spending and savings account and cash deposit services. Koho said it’s still working with Canada Post to enable users to deposit cash into their accounts, “including those we serve in rural and underserved geographic areas of Canada,” but did not comment on how many individuals are using the service or if demand has grown.
Ian Lee, an associate business professor at Carleton University who was employed by Canada Post in corporate finance and banking in the 1980s, is another skeptic. He calls the recent attempts to establish postal banking a temporary and “performative” lifeline for a dying postal service.
“They’re trying to show that they’re trying to respond to the crisis they’re in – a crisis of their existence,” Mr. Lee said. Meanwhile, “cash is in steep, steep decline.”