
Open this photo in gallery:
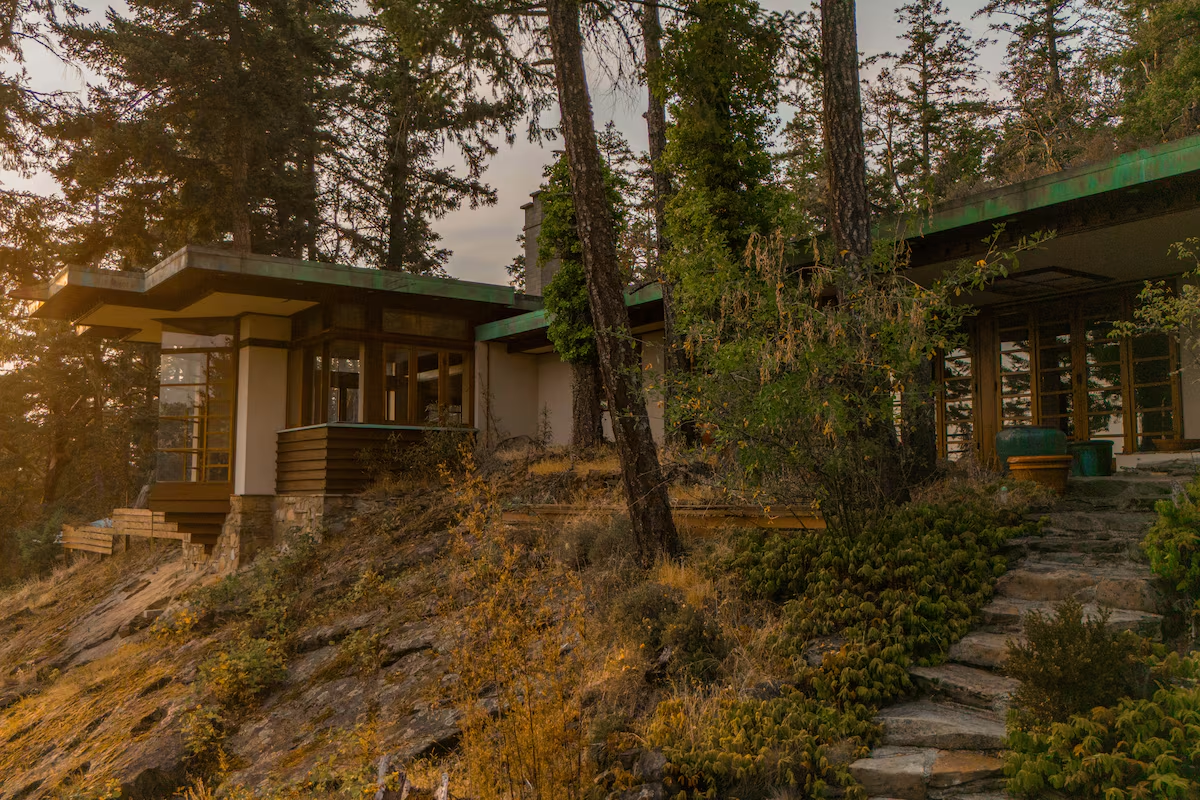
The Home of the Week is a Frank Lloyd Wright-inspired refuge on B.C.’s Pender Island.Nicole Eastman/Nicole Eastman
This week: Why your property tax bills are a ticking time bomb, and an unconventional way to save for a downpayment. Plus, the case against making mortgage interest payments tax-deductible, and one property worth a look.
Take our business and investing news quiz
Property tax
Ontario homeowners are sitting on a ticking tax bomb
Open this photo in gallery:
The valuations Ontario municipalities use to calculate your property bills have been frozen for six years, and many homeowners could be in for a shock if the freeze ends.COLE BURSTON/The Canadian Press
If you own a home in Ontario, be prepared to take cover. Ever since the province froze the price estimate that municipalities use to calculate property taxes in 2020, your bills have been a ticking time bomb. And as Jeff Gray reports, lifting the freeze could have explosive political and financial consequences – but so could leaving it in place.
As you probably well know from your property tax bills, the freeze at 2016-assessed values hasn’t stopped municipalities from raising property tax rates. But if Premier Doug Ford ends the six-year halt, people whose home values rose more than the average in their communities are in for some major sticker-shock when their next bills come in. On the other hand, if your home sank in value, you’ve probably been paying more than you otherwise would have, perhaps by thousands of dollars a year.
So is it time to rip the Band-Aid off? Not everyone agrees, and the Ontario government says it’s consulting on the issue. But if you’re curious about whether you’ve been overpaying or might see your property tax bill skyrocket if the freeze lifts, read Jeff’s story on which homeowners have been most affected.
My First Home
How house-sitting helped a Yellowknife couple save up a $72,000 downpayment
Open this photo in gallery:
House-sitting is an unconventional path to homeownership, but it worked for this couple.Illustration by Diana Bolton
Could you live for 18 months with no permanent address? One couple decided to give up renting and house-sit full-time in order to save for a downpayment. And while no path to homeownership is easy, not paying rent certainly helps.
Nicholas, 35, an electrician, had discovered the unconventional savings approach in Yellowknife, where he house sat and took care of pets for three months. Then about a year before he and his 36-year-old fiancée, a speech therapist, planned to move to Whitehorse, they gave up renting full time and decided to house-sit full-time for as long as they could. “I was like, ‘This is pretty sick,’” he told Zahra Khozema. “I get this whole house by myself and I get to enjoy some pets.”
To be sure, there were drawbacks: the chaos of living out of boxes and your car, figuring out where to send mail and moving sometimes every few weeks. But how much did they save, and what did it mean they could afford in Whitehorse? Read the story to see where they landed.
This week’s lowest fixed and variable mortgage rates in Canada
Rates shown are the lowest available for each term/type and category (insured vs. uninsured) as of market close on Thursday, Oct. 1.
Editorial
A clear, simple housing fix (that is also wrong)
Open this photo in gallery:
There are many great ways to reform taxes in Canada, but as the Editorial Board argues, letting homeowners deduct mortgage interest from their taxable income isn’t one of them.Illustration by Dakota McFadzean
If you’re thinking of buying a new home, the idea of being able to deduct your mortgage interest from your taxable income might sound like a good one. Developers are lobbying Ottawa for the change, Rachelle Younglai reported a couple of weeks ago, in hopes it’ll help more buyers afford to purchase newly constructed homes, and would be balanced by the corresponding decrease in their capital-gains exemption when they do choose to sell. However, the Globe’s editorial board argues the proposal is a simple solution to a complex problem that also happens to be wrong.
Just last weekend, we published a number of ways to improve tax policy, increase fairness across generations and boost rental construction. “The mortgage interest idea is – for good reason – not one of them,” writes the Editorial Board. First, it could inflate demand by allowing people to take on bigger payments, driving up prices for everyone. It could also create an incentive where someone comes out ahead by minimizing their down payment, taking on a larger mortgage, and saving more off the deduction – good for them, but not the federal government’s finances.
And what happens when it’s time to retire and they have remorse for taking the deduction that leaves them to foot a higher capital gains bill when they sell? “It’s easy to imagine the people who took the deduction trying to have their cake and eat it too,” argues the board. “But in the real world, nothing would stop them enjoying the immediate benefit and then clamouring in decades to come for special tax treatment. And if there are enough people in this group they could prove a potent political force, difficult to ignore.” Read the full editorial and decide whether you agree.
Design corner
Should you ditch your bathtub for a walk-in shower?
Open this photo in gallery:
You should consider safety, water usage and resale impacts when deciding whether to keep or toss your bathtub, experts say.Ema Peter/Supplied
Rub-a-dub-dub, should you pull the plug on your tub? A recent report found half of industry experts think it’s worth it for a larger shower, and if you also can’t remember the last time you took a bath, you might agree. But while experts say showers are faster, get you cleaner, use less water and help you avoid slips as you age, not everyone agrees tubs should be circling the drain.
Even if you don’t have time for a bubble bath, designers say there are plenty of reasons to keep the soaker. As Matthew Hague writes, parents and kids will have much harder bath times without an actual bath tub, and not having one can also negatively impact your home’s resale value. So if you’re thinking of doing away with your tub, here’s what experts say you should consider before taking the plunge.
Home of the Week
An artist’s Pender Island refuge
Open this photo in gallery:
This custom-built home is a love letter to Frank Lloyd Wright and the late owners’ artistic passions.Nicole Eastman/Nicole Eastman
3326 Port Washington Rd., North Pender Island, B.C – Full gallery here
B.C.’s Gulf Islands have a knack for creating fond memories in every visitor’s mind, but the aptly named Halycon Days home invites you to actually live in the feeling. Designed by jeweller and artist Karl Stittgen, the homage to Frank Lloyd Wright is also a love letter to Stittgen’s second wife, ceramic artist Nora Sasaki, and the late couple’s artistic and hosting inclinations.
The low, horizontal home is not only a setting for creation and salon-like dinner parties, it is a work of art itself. Inside, a mosaic of larger pebbled river-stones borders the floors, where, instead of grout, hand-stained wooden inlays separate tiles of dark exposed aggregate concrete. And throughout the 3,450 square feet of living space, wood – much of it stained to match the Arbutus trees outside – is everywhere. From built-in bunk beds, desks and a library to panelling on the walls and ceilings, there is almost something yacht-like about the home.
The practicalities of hosting are accounted for as well. The kitchen and massive pantry offers plenty of room to cook for an army, but a wooden lattice dividing it from the main room ensures hosts and guests are still connected. Many walls of wood-frame windows, including one that connects the kitchen to the bedrooms, offer ocean views and evoke Japanese sliding walls and screens, allowing sunlight to warm the stone and wood underfoot. And a guest house where visitors can lay their heads manages to pack an impressive amount of design drama into a much smaller version of the main home. Read the full story here.
What do you think is the asking price for the property?
a. $1,089,000
b. $1,349,000
c. $1,689,000
d. $1,949,000
c. The asking price is $1,689,000.